Q3 2026 Market Outlooks
Industrial
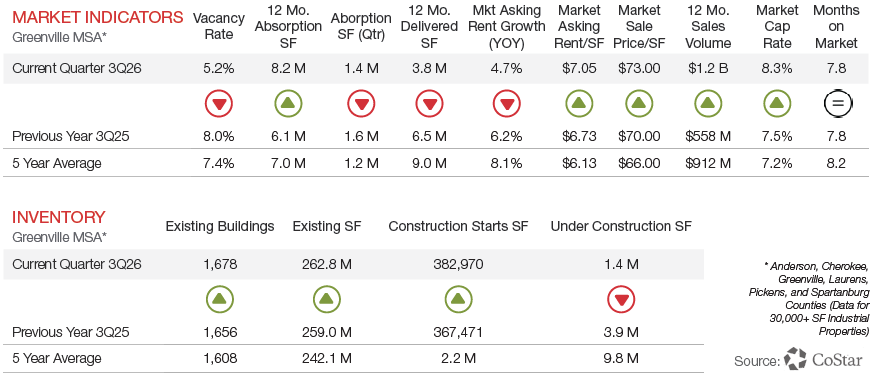
The Upstate’s industrial market continued shifting from oversupply to tightening fundamentals in Q3 2026. Net absorption reached ±2.4 million square feet, up 6.3% quarter-over-quarter, while vacancy fell to roughly 5–7% , with large-block vacancy especially tight. Specifically, few buildings over 900,000 SF are available. New leasing activity approached 7 million square feet year-to-date, led by BMW’s 918,000-SF lease backfilling former DHL space in Spartanburg , plus major leases from Suniva and Detmold Group. Our region also drew significant capital investment, highlighted by USA Rare Earth’s $1.2 billion commitment.
Construction continued to contract, falling to 2.1 million square feet underway — down 42% year-over-year and a steep drop from the 8.9 million square feet under construction in early 2024 — as developers work through the historic 2023–2024 supply wave. Cherokee County emerged as a standout growth area, closing the competitive gap with Charlotte through lower land costs and strong incentives.
Tightening vacancy, slowing new supply, and renewed rent growth are expected as 2026 progresses. (Shareholder Hunter Garrett, CCIM, SIOR)
READ FULL INDUSTRIAL REPORT HERE
Office
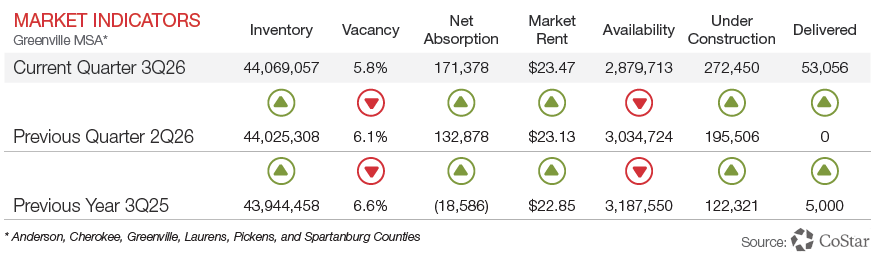
Greenville’s office market tightened further in the third quarter. Vacancy fell to 6.5%, down a full point from a year ago and well below the 10-year average of 7.5%, supported by roughly 169,000 square feet of net absorption in Q3 alone. Asking rents now average about $27.40 per square foot, up 2.4% year over year, and landlords remain firmly in control of most negotiations. Outside of a handful of buildings marketing large blocks of space, tenants are finding limited options and modest concessions, particularly for small and mid-sized requirements. New supply won’t change that anytime soon. Nearly all of the 272,000 square feet under construction is preleased healthcare or owner-user space, with nothing underway downtown or along Pelham Road. Investors have taken notice, as trailing 12-month sales volume reached $262 million, ahead of the five-year average, with fully leased buildings commanding a clear premium. Heading into 2027, we expect conditions to remain tight. Tenants facing lease expirations over the next 12 to 24 months should start the process early, because quality space and favorable terms are going to the users who move first. (Senior Associate John Stathakis, CCIM)
Retail
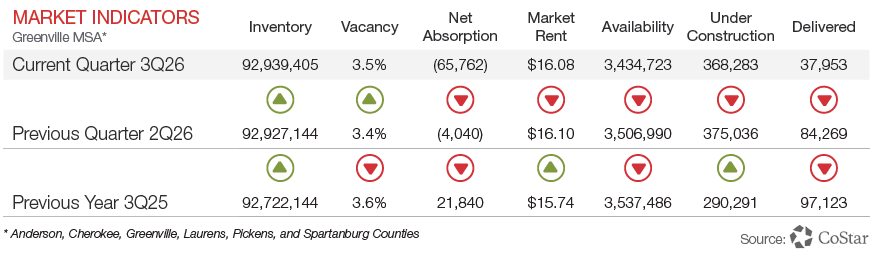
The Upstate of South Carolina retail market continues to demonstrate strong fundamentals heading into the latter half of 2026. Population and employment growth remain the primary drivers of retail demand, with Greenville-Spartanburg now supporting more than one million residents and continued residential expansion pushing retail activity into emerging suburban corridors. Available quality retail space remains limited, creating a competitive environment for tenants and continued pricing power for well-positioned landlords.
From a development standpoint, elevated construction costs, financing conditions and limited availability of development sites continue to constrain new supply. This dynamic is creating opportunities for developers who can secure well-located land and deliver projects that align with the needs of growing residential communities. Grocery-anchored centers, restaurants, service-oriented tenants and other necessity-based uses remain particularly well-positioned.
For owners and investors, the market continues to favor high-quality assets with strong locations, durable tenant mixes, and opportunities to enhance value through leasing or redevelopment. For retailers, early site selection and proactive planning remain increasingly important as competition for the best locations intensifies. (Associate Jake Scott)